Going under contract feels like the finish line. It isn't. In my experience, the biggest mistake buyers make right after their offer is accepted is acting like the house is already theirs and going quiet with their lender. Under contract just means you've earned the opportunity to complete the purchase. The next 30 days decide whether you actually close.
Most Tampa Bay resale homes are written on the Florida Realtors/Florida Bar "AS IS" Residential Contract for Sale and Purchase. Every deadline in it runs from the Effective Date, the day the last of the buyer and seller signs or initials and delivers the final offer or counteroffer. Here's what that clock looks like when the blanks are left empty.
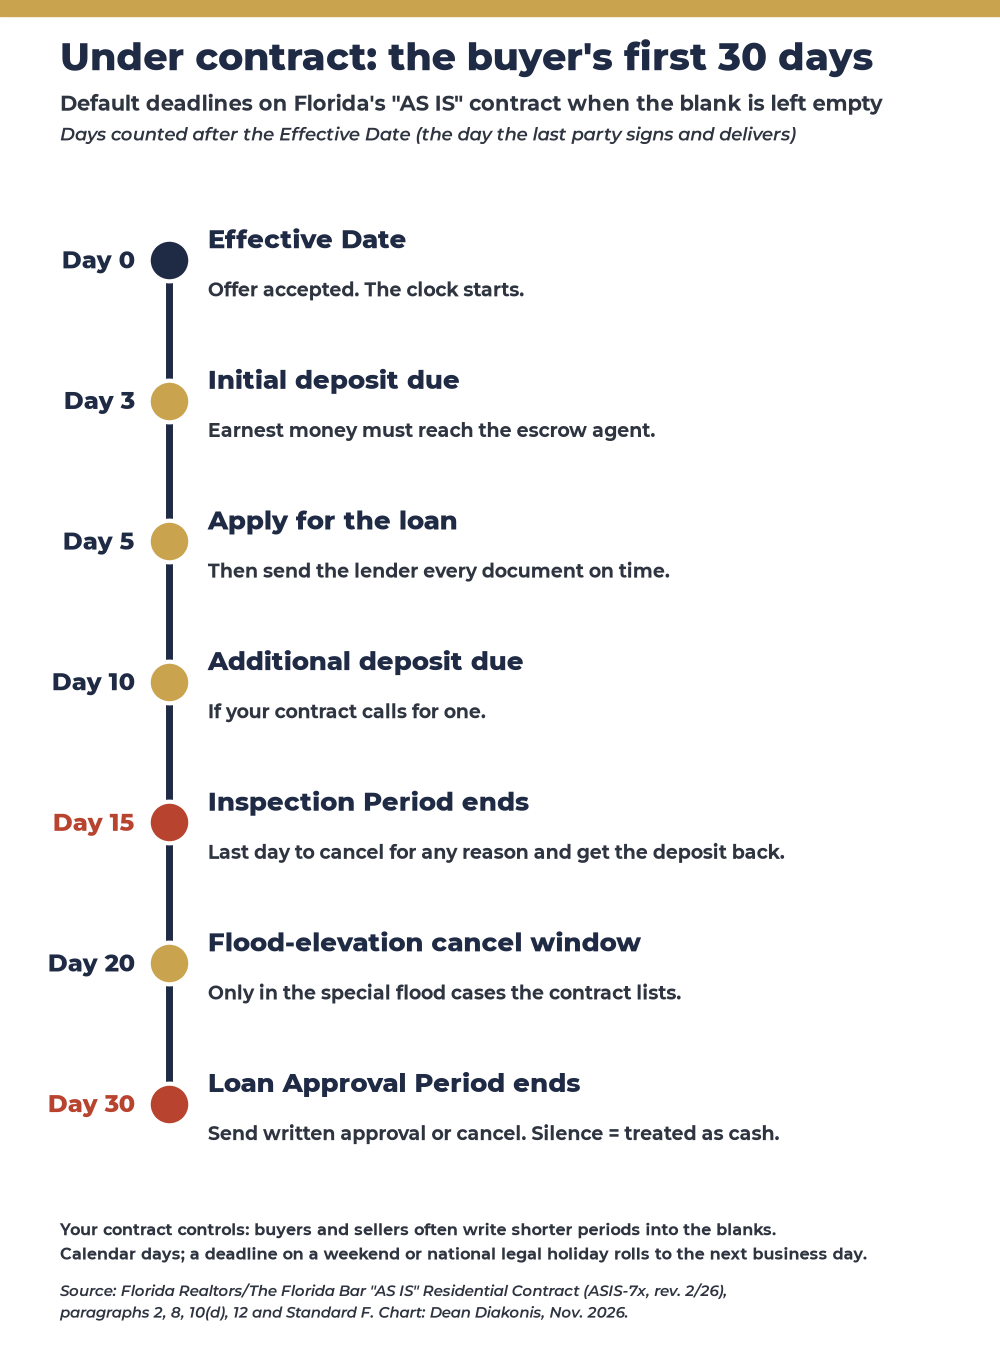
Default deadlines on the Florida Realtors/Florida Bar "AS IS" contract (ASIS-7x) when the blanks are left empty. Your signed contract controls. Source: Florida Realtors/The Florida Bar.
Those are the form's fallback numbers. Your contract may say something different, and in a competitive deal it often does: shorter inspection periods and shorter loan approval periods are common negotiating chips. Read your own deadlines, put them in your calendar, and treat them as real.
Day 3: Get the earnest money in
Unless the initial deposit went in with your offer, the form gives you the number of days written in, or 3 days after the Effective Date if that blank is empty, to get it to the escrow agent named in the contract. An additional deposit, if your contract has one, defaults to 10 days. Plan the transfer before you sign, not after. And verify wire instructions by calling the title company or escrow agent at a number you looked up yourself, never one from an email.
Day 5 and every day after: Stay on top of your lender
If you're financing, the form requires you to apply for the loan within the days written in (5 if blank) and to use "good faith and diligent effort" to get approval. The contract spells out that this includes getting your lender the documents it asks for on time. Failing to do that isn't just inconvenient. Under the form, it's a default.
This is the part I see buyers underestimate most. When a pay stub, bank statement or letter of explanation sits in someone's inbox for three days, a few things happen:
- The file stalls and the timeline slips.
- The seller notices and gets irritated, and that goodwill matters later.
- You lose leverage in inspection negotiations, because it's hard to ask for repair credits while you're the one holding up the deal.
- If you need more time, an extension is a much harder ask when the seller already thinks you're dragging your feet.
My advice is simple: answer your lender the same day, every time, until you have the keys.
Day 15: The Inspection Period ends
On the AS IS form, the Inspection Period is the days written in, or 15 days if blank. Until it ends, you can cancel in your sole discretion by written notice and get your deposit back. Once it passes without a written cancellation, you've accepted the home's physical condition. A phone call to the listing agent is not a cancellation.
That window goes fast, so book inspectors in the first few days. In Tampa Bay that usually means more than a general home inspection. Insurance companies commonly ask for a 4-point inspection on older homes, a wind mitigation report can affect the premium, and a wood-destroying organism inspection is worth having. Get real insurance quotes during this period too, including flood. If the home is likely to end up with Citizens, read up on the flood insurance requirement that takes its final step on Jan. 1, 2027. A surprise premium is much easier to deal with on day 6 than on day 25.
Day 20: The flood-elevation window
The form also gives buyers a separate cancellation right, 20 days if blank, but only in specific situations it lists: the home is in a FEMA Special Flood Hazard Area or Coastal Barrier Resources Act area and either its lowest floor sits below the minimum flood elevation or it can't get flood insurance through the NFIP or a private carrier. It's narrow, but in coastal Pinellas, South Tampa and along the Gulf it's worth knowing it exists.
Day 30: Loan approval, in writing
The Loan Approval Period defaults to 30 days. Before it ends, you need to send the seller written notice that you have loan approval, written notice that you're satisfied you'll get it and can close, or a written cancellation if you couldn't get approved despite good-faith effort. Here's the trap: if you send none of those, the form treats the deal as if you'd checked the cash box from the start. The seller then gets 3 days to cancel, and if they don't, you're moving forward without your financing contingency. Your agent and lender should be tracking this date, and so should you.
Buying a condo or a home with an HOA?
Florida law adds its own windows on top of the contract. On a condo resale, the contract must either confirm you received the association documents more than 7 days before signing (not counting weekends and legal holidays) or let you cancel within 7 of those days after signing and receiving the declaration, bylaws, rules, budget, financial statement and FAQ document (Fla. Stat. 718.503). In an HOA community, if you didn't get the required disclosure summary before you signed, you can cancel within 3 days of receiving it or before closing, whichever comes first (Fla. Stat. 720.401). Those documents only help if you actually read them while the window is open.
Your first-week checklist
- Write every contract deadline on your calendar the day the contract is signed.
- Get the deposit to escrow early, after confirming wire instructions by phone.
- Submit the full loan application and answer every lender request the same day.
- Book the home inspection, 4-point, wind mitigation and WDO inspections right away.
- Get homeowners and flood insurance quotes before the Inspection Period ends.
- If it's a condo or HOA, read the association documents now, not the week of closing.
Going under contract is the start of the real work. If you're getting ready to buy, my Tampa Bay buyer's page walks through the rest of the process, and veterans can read my VA loan guide.
This article explains the default terms of a standard Florida contract form and is general information, not legal advice. Your signed contract controls. Talk to a Florida real estate attorney about your specific rights.
Sources
- Florida Realtors: current FR/Bar and FR/Bar AS IS contract forms (ASIS-7x), released Feb. 27, 2026
- Florida Realtors: educational sample of the "AS IS" Residential Contract for Sale and Purchase (deposit, financing, inspection and Standard F timing provisions)
- Florida Statutes 718.503 (2026): condominium resale disclosure and cancellation
- Florida Statutes 720.401 (2026): HOA disclosure summary and cancellation