If your Tampa Bay home is insured with Citizens Property Insurance, there's a date to put on the calendar now: January 1, 2027. For Citizens personal residential policies that include wind coverage and take effect (new or renewal) on or after that date, flood insurance becomes a condition of eligibility for the remaining homes that weren't already covered by earlier steps. It doesn't matter what the home is worth or what flood zone it's in.
This has been phasing in since 2023, and the final step is about seven weeks away. Here's what it means for owners, buyers and sellers in Hillsborough, Pinellas and Pasco.
What the law actually says
Florida Statute 627.351(6)(aa) requires Citizens to make flood insurance a condition of coverage for personal lines residential risks. It phased in like this:
- 2023: homes in a FEMA Special Flood Hazard Area (new policies from April 1, 2023; renewals from July 1, 2023).
- January 1, 2024: dwelling replacement cost of $600,000 or more.
- January 1, 2025: $500,000 or more.
- January 1, 2026: $400,000 or more.
- January 1, 2027: all other personal lines residential property insured by Citizens.
Two kinds of Citizens policies are exempt: policies that don't cover wind, and condominium unit-owner policies. So if you own a condo and carry a Citizens HO-6-type policy, this rule doesn't apply to your unit policy (your association's master coverage is a separate question for the board).
The requirement is for dwelling coverage. A 2024 change removed the contents requirement, according to the Florida Department of Financial Services' Insurance Consumer Advocate. The flood policy can come from the National Flood Insurance Program or a private flood policy that meets the standards in Florida law.
A bill this year, SB 1024, would have carved out more exemptions. It died in the Senate Banking and Insurance Committee on March 13, 2026, so the 2027 step stands as written.
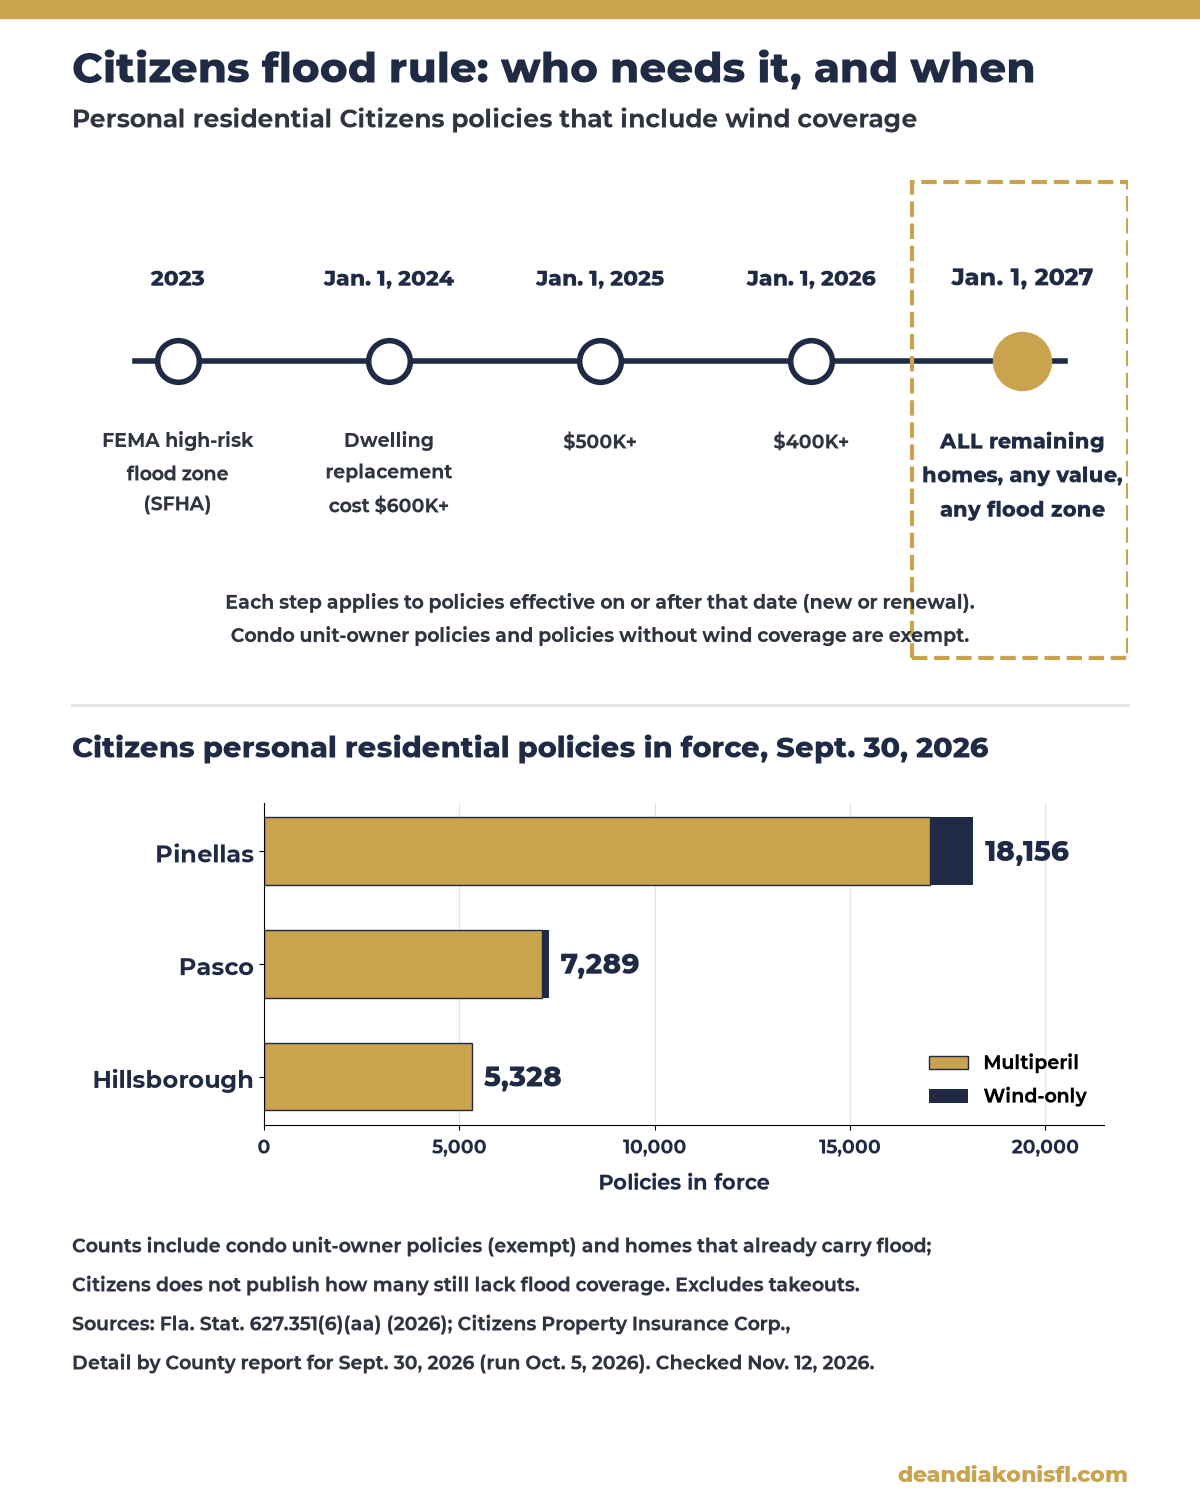
Citizens flood requirement phase-in under Fla. Stat. 627.351(6)(aa), and Citizens personal residential policies in force by county as of Sept. 30, 2026. Sources: Florida Statutes; Citizens Property Insurance Corp.
How many Tampa Bay policies are we talking about?
Citizens' own Detail by County report for September 30, 2026 (the most recent one posted when I checked on November 12) shows these personal residential policies in force:
- Pinellas: 18,156 (17,058 multiperil plus 1,098 wind-only)
- Pasco: 7,289 (7,117 multiperil plus 172 wind-only)
- Hillsborough: 5,328 multiperil
Not every one of those is affected. The counts include condo unit-owner policies, which are exempt, and plenty of homes that already carry flood because they're in a high-risk zone, are worth more than $400,000 to rebuild, or have a mortgage lender that required it. Citizens doesn't publish how many still lack flood coverage, so I'm not going to guess. The point is that Pinellas has by far the most Citizens exposure in our area, and the policies left for the 2027 step are mostly lower-replacement-cost homes outside the high-risk zones. Those are exactly the owners who may never have priced flood insurance.
The timing trap: the 30-day wait
New NFIP flood policies generally have a 30-day waiting period before coverage starts, according to the FEMA NFIP Flood Insurance Manual. There's an exception when the flood policy is bought in connection with a mortgage loan closing. For an existing owner just renewing with Citizens, though, the wait usually applies.
In practice: the requirement kicks in with your first Citizens policy that's effective on or after January 1, 2027. If your Citizens renewal is in January or February, you'll want flood coverage bound well over 30 days before that renewal date. Pull up your declarations page, find the effective date, and count backward. Private flood carriers set their own waiting periods, so ask.
If you're buying a home with Citizens coverage
- Price flood insurance during your inspection period, not after. If the home will be on Citizens, flood is part of your real monthly cost. Plug it into the mortgage calculator with taxes and HOA dues.
- Ask whether the seller has an NFIP policy. FEMA's guide for real estate professionals notes a seller can transfer an NFIP policy to the buyer. Sometimes that's a better deal than starting a new one.
- Read the flood disclosure. Under Florida Statute 689.302, sellers of residential property must give buyers a flood disclosure at or before contract. It covers known flood damage during their ownership, flood insurance claims (including NFIP), and federal flood assistance such as FEMA aid. A "yes" doesn't kill a deal. It tells you what to ask next.
- Look up the flood zone yourself on the FEMA Flood Map Service Center. Zone X doesn't get you out of the Citizens requirement in 2027, but it usually affects the price.
More on the buying side: my buyer resources and the four-point inspection surprises that can also change what insurance costs.
If you're selling
Buyers will price this in, so get ahead of it. If you already carry flood insurance, have the declarations page ready. If the home is on Citizens and you don't carry flood, find out what a policy would cost before you list. That way the first number a buyer hears comes from you, not from a nervous call to their agent halfway through the inspection period. And fill out the flood disclosure carefully. It's a legal form, not a formality.
If you're weighing timing or price, start with a home valuation or my seller resources.
What this isn't
I'm a realtor, not an insurance agent. This is a plain-English summary of the law and Citizens' published rules, not coverage advice for your house. Your licensed insurance agent can tell you what your Citizens policy needs, whether NFIP or private flood fits better, and what it will cost. If you're also tracking other 2026 homeowner changes, see my posts on Amendment 3 and this year's property tax bills.
Sources (checked November 12, 2026)
- Florida Statutes 627.351(6)(aa) (2026), Citizens flood insurance requirement
- Citizens Property Insurance: Flood Insurance Requirements
- Citizens Detail by County, period ending September 30, 2026
- Florida DFS Insurance Consumer Advocate: Property Insurance Changes
- Florida Senate: SB 1024 (2026) bill history
- FEMA NFIP Flood Insurance Manual (October 2025)
- FEMA: Flood Insurance Q&A for Real Estate Professionals
- Florida Statutes 689.302 (2026), seller flood disclosure
Photo: "Late afternoon on Snell Isle, St Petersburg Florida 2020" by Calmuziclover, Wikimedia Commons, CC BY 2.0, cropped.